Why Military Buyers Get Denied VA Loans in SC (and How to Fix It)

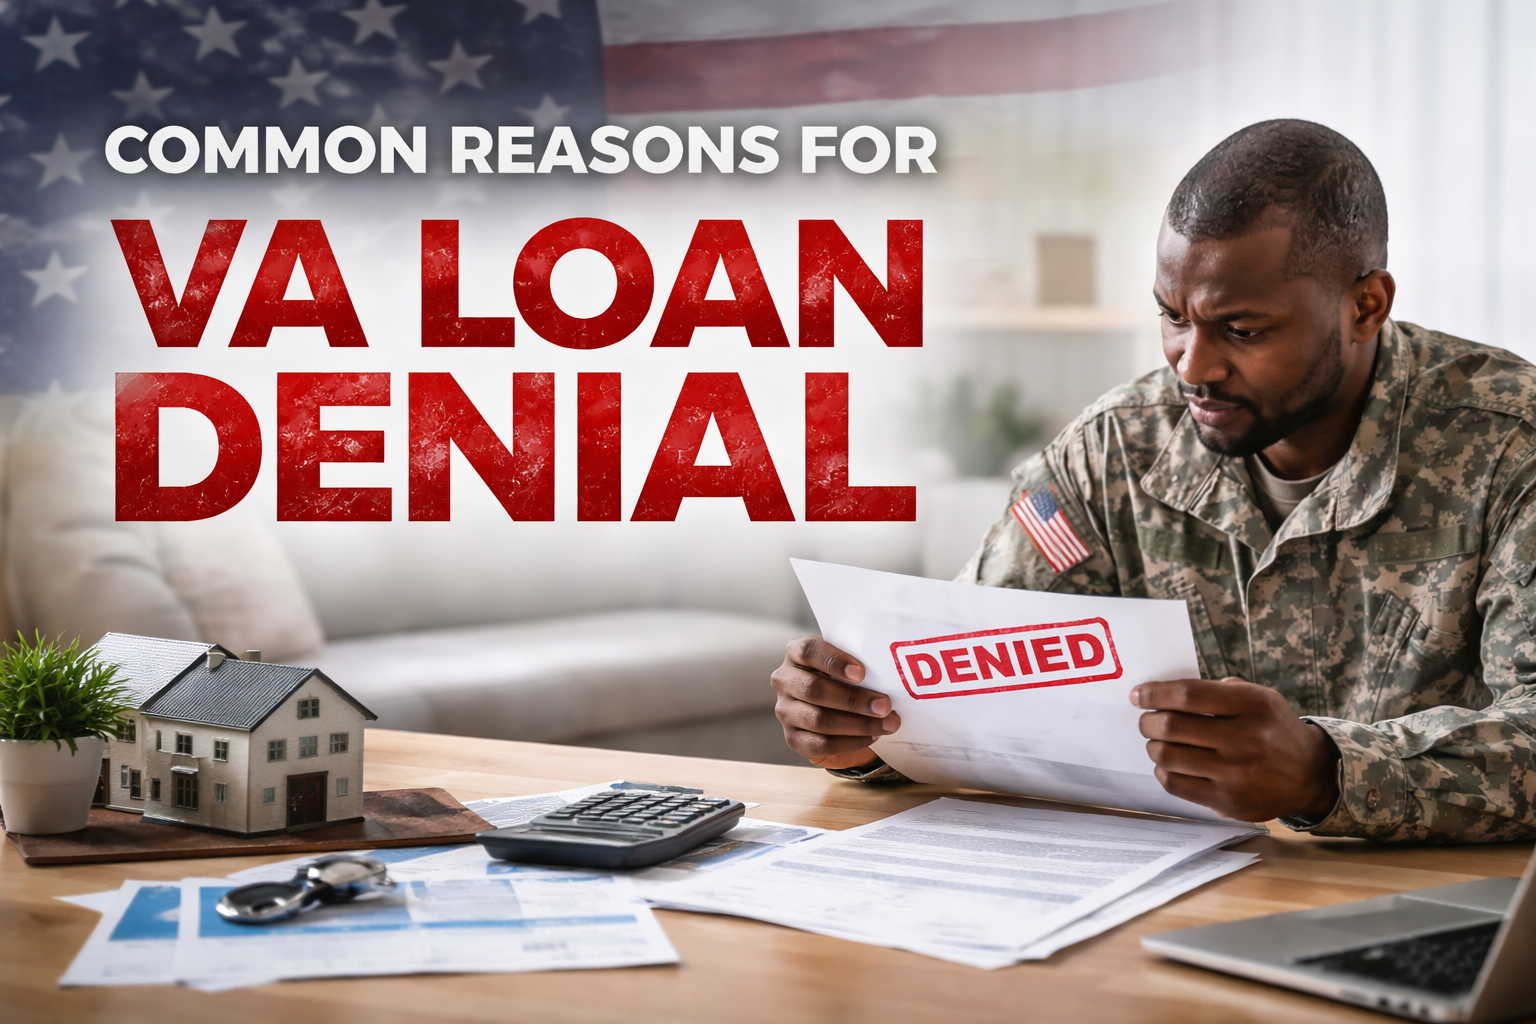
Common Reasons For Va Loan Denial
VA loans are designed to help military members, veterans, and eligible spouses achieve homeownership with more flexible requirements than many conventional loan programs. Even with these advantages, approval is not guaranteed. Lenders still evaluate your financial profile carefully to ensure you can manage long term mortgage payments responsibly.
One of the most common reasons for denial is a high debt to income ratio. This means a large portion of your monthly income is already going toward existing obligations such as credit cards, auto loans, student loans, or personal loans. When this ratio becomes too high, lenders may worry that adding a mortgage payment could stretch your finances too thin. Even if you have a high income, too much existing debt can create concern about long term affordability.
Credit challenges are another major factor. While VA loans are more flexible with credit compared to many other loan programs, lenders still review your credit history closely. Late payments, accounts in collections, charge offs, or a consistently low credit score can signal risk. Lenders want to see that you have a pattern of responsible borrowing and repayment over time. A single issue may not always cause denial, but multiple negative marks can significantly impact your approval chances.
Income stability is also very important. Lenders prefer borrowers who have consistent and predictable income. Frequent job changes without a clear employment pattern, gaps in employment, or irregular income can raise concerns. The goal is to confirm that your income is reliable enough to support a monthly mortgage payment not just now but in the future.
Understanding Credit Requirements
Although the Department of Veterans Affairs does not set a strict minimum credit score, most lenders still apply their own requirements. These are commonly referred to as lender guidelines. Each lender can set different standards depending on their risk tolerance, which means two lenders may evaluate the same applicant differently.
If your credit score falls below a lender’s requirement, your application may be denied even if you technically qualify under VA guidelines. This is why it is important to understand that approval depends not only on VA rules but also on lender specific policies.
Improving your credit score can significantly increase your chances of approval. One of the most effective steps is paying all bills on time consistently. Payment history is one of the biggest factors in credit evaluation. Reducing credit card balances can also help because it lowers your credit utilization, which shows lenders that you are not overextended. Avoiding new debt during the application process is equally important since new accounts can temporarily lower your score or increase your debt obligations.
Property Related Issues
Sometimes the issue is not the borrower but the property itself. VA loans require homes to meet specific safety, livability, and structural standards. This is determined through a VA appraisal process that goes beyond simple market value. The property must be safe, sound, and sanitary.
If a home has significant issues such as roof damage, electrical problems, plumbing concerns, or structural defects, it may not pass the VA appraisal. These conditions must typically be corrected before the loan can move forward. This is especially common with older homes or properties that have been poorly maintained over time.
In some cases, buyers may be able to negotiate repairs with the seller. However, if the seller is unwilling or unable to make the required improvements, the loan may be denied for that property. When this happens, buyers often need to continue their search for a home that meets the required standards.
Insufficient Documentation
Another common reason for delays or denials is missing or incomplete paperwork. Lenders require detailed documentation to verify your eligibility and financial situation. This typically includes your Certificate of Eligibility, proof of income, recent pay stubs, tax returns, bank statements, and employment verification. When documents are missing or inconsistent, lenders cannot properly evaluate your application. This can lead to delays, additional requests, or even denial if the required information is not provided in time. Staying organized throughout the process is essential. Responding quickly to lender requests and submitting complete documentation helps keep your application moving forward smoothly. It also reduces the risk of miscommunication or unnecessary setbacks.
How To Fix Debt To Income Issues
If a high debt to income ratio is the problem, there are several ways to improve your situation. One of the most effective strategies is reducing existing debt. Paying off credit cards, personal loans, or other recurring obligations can quickly improve your financial profile. Another approach is increasing your income if possible. This could include overtime work, additional part time income, or other verifiable sources of earnings. Even small increases in income can have a meaningful impact on your debt to income ratio and overall loan eligibility. In some cases, restructuring debt may also help. Consolidating high interest accounts into a more manageable payment can improve monthly cash flow and make your financial picture more favorable to lenders.
How To Recover From A Denial
A loan denial can feel discouraging, but it does not mean your homeownership journey is over. In many cases, it simply means there are specific areas that need improvement before reapplying. The first step is understanding the exact reason for the denial. Lenders are required to provide an explanation, which gives you a clear starting point for improvement. Once you know the issue, you can create a focused plan to address it. This may involve improving your credit, lowering your debt, building savings, or correcting documentation issues. With time and consistency, many applicants are able to reapply successfully after making the necessary adjustments.
Working With The Right Professionals
Having the right support can make a major difference in your VA loan journey. Experienced lenders and real estate professionals who understand VA loan guidelines can help you avoid common mistakes and navigate challenges more effectively. They can also identify potential issues early in the process so you are not surprised later. This proactive guidance can save time, reduce stress, and improve your chances of approval. A knowledgeable professional can also help you understand what lenders are looking for and how to position your application in the strongest possible way.
The Importance Of Pre Approval
Pre approval is one of the most important steps before starting your home search. It gives you a clear understanding of how much you may qualify for and what conditions may need attention before final approval. During pre approval, lenders review your financial information and identify any potential concerns early. This allows you to address issues in advance instead of discovering them after you have already found a home. Being pre approved also helps you shop with confidence. It shows sellers that you are a serious buyer and can strengthen your position when making an offer.
Final Thoughts For Military Buyers In SC
Being denied a VA loan can be frustrating, especially when you are eager to purchase a home in SC. However, most denials are not permanent obstacles. They are simply signals that certain areas of your financial profile or documentation need improvement.
With the right plan, support, and preparation, many buyers are able to overcome these challenges and achieve successful approval. Whether it involves improving credit, reducing debt, or selecting a better suited property, each step brings you closer to homeownership.
If you have been denied or want to make sure you are fully prepared before applying for a VA loan in SC, contact us today. We will review your situation, help you identify what needs to be improved, and guide you step by step toward successful homeownership with confidence.
Categories
Recent Posts

"Molly's job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "