How Much House Can Military Families Afford in SC
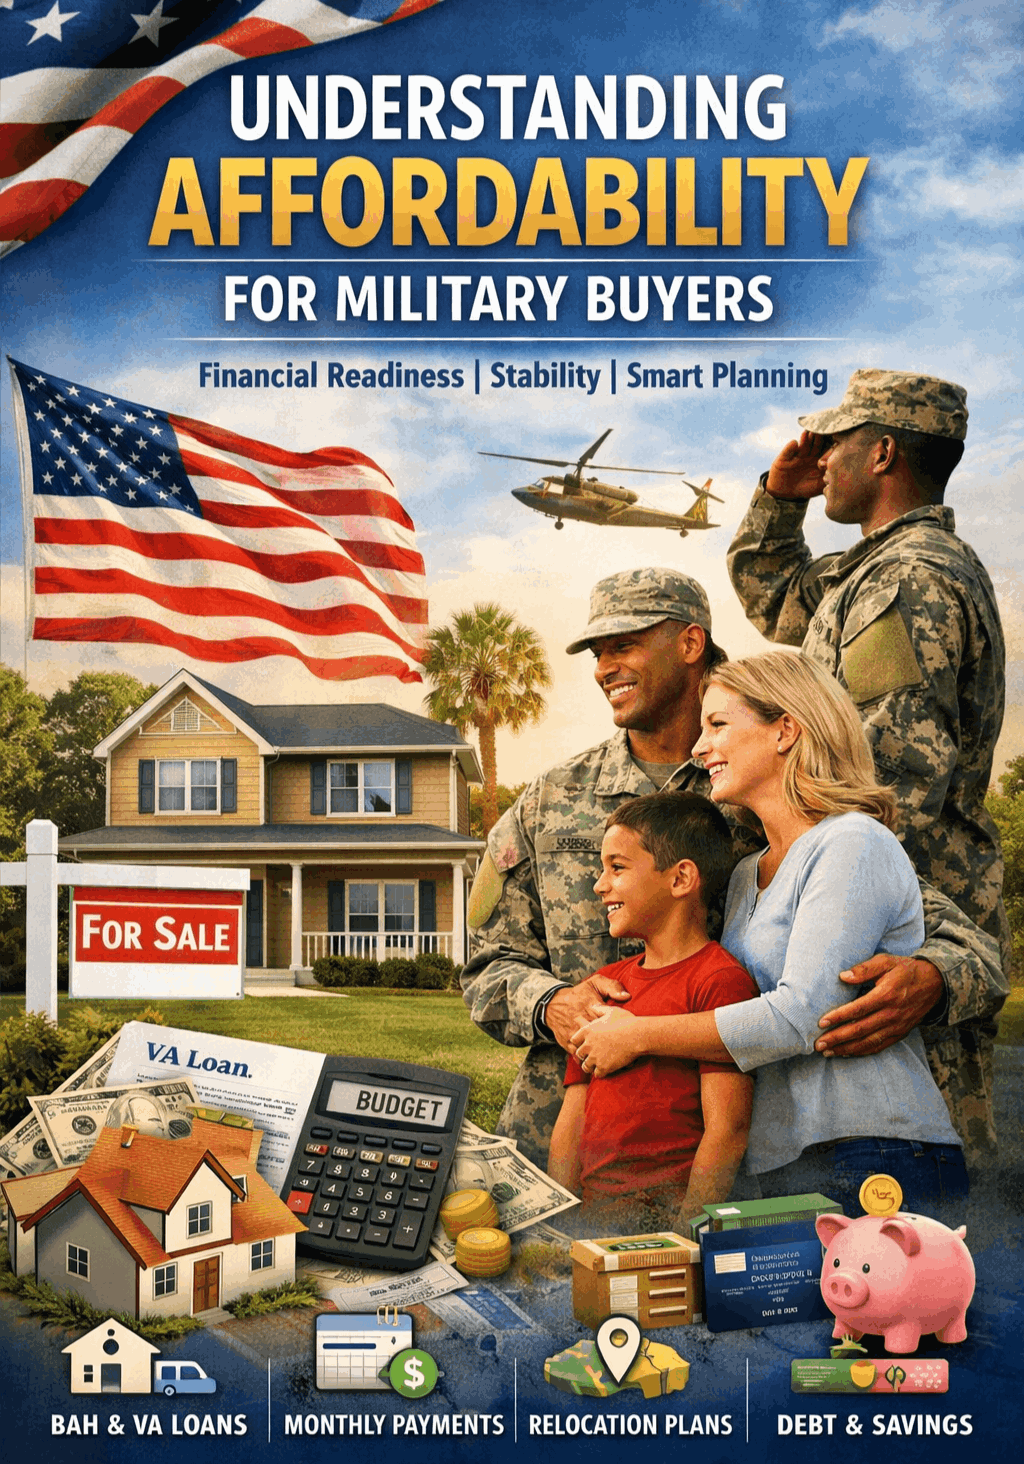
Affordability is more than just a simple price range or a maximum loan approval amount. For military families in South Carolina, it is a combination of financial readiness, long term stability, and lifestyle planning. Buying a home is one of the biggest financial commitments you will make, and understanding what you can truly afford helps you make confident decisions without unnecessary stress later on.
Many buyers focus only on the home price they are approved for, but real affordability goes deeper. It includes how comfortable you feel with the monthly payment, how secure your job situation is, how often you may relocate, and how prepared you are for unexpected expenses. When all of these factors are considered together, you get a clearer and more realistic picture of your actual buying power.
For military families in SC, affordability also has a unique advantage because of benefits like housing allowances and VA loan flexibility. These benefits can significantly improve purchasing power, but they should still be used wisely to avoid overextending your budget.
Factors That Determine Your Budget
Your budget starts with your income, but it does not end there. Lenders take a full financial snapshot to determine how much you can comfortably afford.
Your base military income is the foundation of your qualification. This includes your monthly pay based on rank and years of service. In many cases, lenders also consider additional verified income sources such as spouse income, part time work, or consistent secondary earnings.
One of the most important components in military affordability is the Basic Allowance for Housing. This benefit is often treated as qualifying income when applying for a VA loan. Because it helps cover housing costs, it can significantly increase the price range you are approved for. However, it is still important to understand how it fits into your overall financial picture rather than relying on it alone.
Debt to income ratio is another critical factor. This measures how much of your monthly income goes toward existing debts such as car loans, credit cards, student loans, or personal loans. Even if your income is strong, high monthly debt obligations can reduce your borrowing capacity. A lower debt to income ratio typically results in better loan approval terms and more flexibility in home selection.
Your credit profile also plays a major role. Credit score and credit history help lenders evaluate how responsibly you manage debt. A higher score can open the door to better interest rates, which directly impacts your monthly mortgage payment and overall affordability. Even small changes in interest rates can significantly affect long term costs.
Savings should also be considered. While VA loans often do not require a down payment, buyers still need funds for closing costs, inspections, moving expenses, and initial home setup. Having reserves gives you financial stability and reduces stress during the transition into homeownership.
Breaking Down Your Monthly Housing Costs
Affordability is not just about qualifying for a loan amount. It is about understanding the full monthly cost of owning a home. Your mortgage payment typically includes principal and interest, but that is only part of the picture. Property taxes, homeowners insurance, and potentially homeowners association fees are also included in your total monthly housing expense. In SC, property taxes are generally lower compared to many other states, which can make homeownership more affordable for military families stationed in the region. However, exact costs still vary depending on the county, home value, and local tax rates. Insurance costs can also differ based on location and property type. When you add all these components together, you get your true monthly housing obligation. Understanding this full number helps you plan more accurately and avoid surprises after closing.
How BAH Impacts Your Buying Power
Basic Allowance for Housing is one of the most powerful advantages for military buyers. Lenders often include BAH when calculating your qualifying income, which increases your approved loan amount and expands your home search options. However, just because you qualify for a higher price does not always mean you should spend up to that limit. BAH is designed to support housing costs, but your comfort level should still guide your decision. Choosing a home within a reasonable range gives you financial breathing room for other priorities such as savings, travel, family needs, and future relocation plans. A smart approach is to view BAH as a tool for flexibility rather than a maximum spending limit.
The Importance Of Pre Approval
Pre approval is one of the most important steps in the home buying process. It gives you a realistic understanding of your budget before you start looking at homes. During pre approval, lenders review your income, credit, debt, and documentation to determine how much you can qualify for. This process helps identify any potential issues early so you have time to fix them before making an offer on a home. Pre approval also strengthens your position as a buyer. Sellers are more likely to take your offer seriously when they know your financing has already been reviewed. In competitive markets, this can make a significant difference in whether your offer is accepted.
Common Mistakes Military Buyers Make
One of the most common mistakes is purchasing a home at the very top of the approved budget. While it may seem appealing to maximize your approval amount, it can lead to financial strain if unexpected expenses arise. Another mistake is underestimating the total cost of homeownership. Many buyers focus only on the mortgage payment and forget about maintenance, utilities, repairs, and potential upgrades. These costs can add up over time and affect your overall budget. Some buyers also skip or delay pre approval, which can lead to disappointment later. Without a clear understanding of your financial limits, it is easy to fall in love with a home that is outside your actual budget.
Smart Strategies For Staying Within Budget
A strong strategy for affordability is to set a comfortable price range rather than focusing only on your maximum approval amount. This gives you flexibility and reduces financial pressure. It is also important to think long term. Military life often involves relocation, deployments, or changes in duty station. Choosing a home that fits your future plans can help you avoid financial challenges later. Maintaining an emergency fund is another key strategy. Unexpected repairs, job changes, or life events can happen at any time. Having financial reserves gives you peace of mind and stability as a homeowner.
Final Thoughts On Affordability In SC
Understanding affordability is one of the most important steps in building a successful home buying plan. It is not just about how much you can qualify for, but about what you can comfortably sustain over time. For military buyers in SC, benefits like VA loans and BAH provide strong advantages, but they work best when combined with careful planning and realistic budgeting.
If you want a personalized affordability breakdown based on your military income, benefits, and financial situation in SC, contact us today. We will help you understand your numbers clearly and guide you toward a home that fits both your budget and your future goals.
Categories
Recent Posts

"Molly's job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "